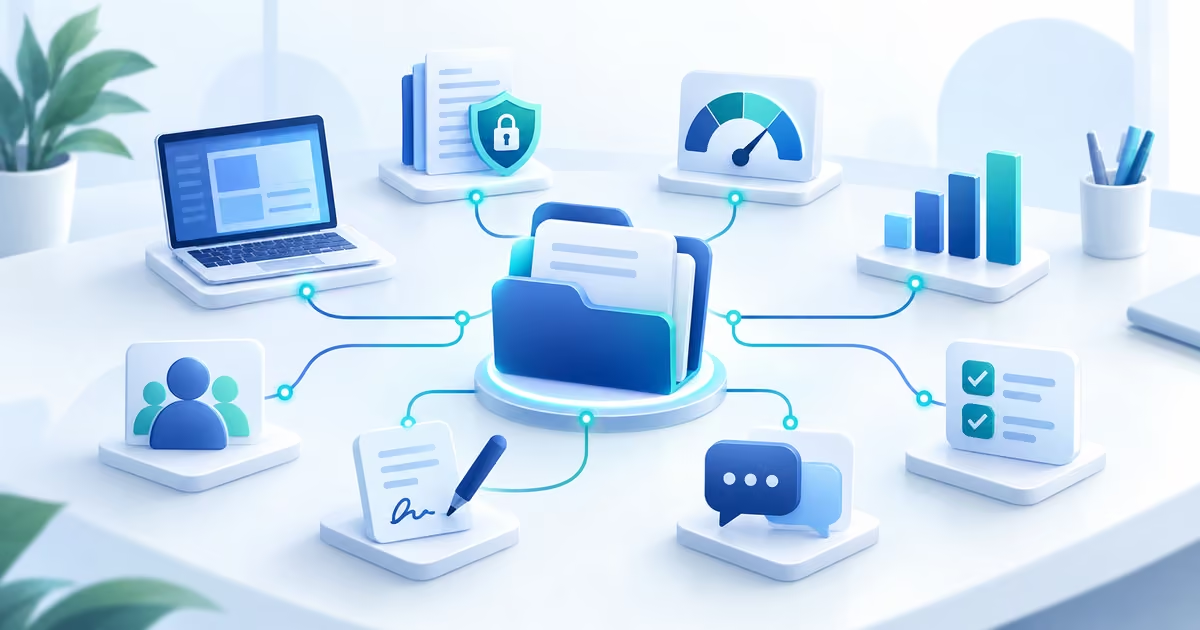
Mortgage broker tools fall into nine categories: loan origination software, a borrower point-of-sale portal, document collection, credit reporting, a product and pricing engine, a CRM, a loan officer website, e-signature, and team messaging. You do not need nine separate products. You need each job covered once, with data that moves between tools without anyone retyping it.
This guide explains what each category does, what to check before you buy, and how to decide between one platform and a set of separate tools.
Key takeaways
- A brokerage needs nine jobs covered, from capturing leads to submitting clean files to lenders.
- The biggest hidden cost is duplicate data entry between tools, not the subscription fees.
- Ask every vendor how a file gets to your lenders. A standard export such as MISMO 3.4 beats manual re-entry.
- Some categories, like pricing engines and CRMs, are specialist tools. Plan for them even if your core platform does not include them.
What tools do mortgage brokers use?
| Tool category | The job it does | Priority |
|---|---|---|
| Loan origination software | Holds the pipeline and every loan file | Core |
| Point-of-sale and borrower portal | Takes the application and shows borrowers their status | Core |
| Document collection | Gathers and organizes borrower and third-party documents | Core |
| Credit reporting | Pulls tri-merge credit with the borrower's authorization | Core |
| Product and pricing engine | Compares loan programs and pricing across wholesale lenders | Core for most brokers |
| CRM and marketing | Tracks contacts, follow-ups and referral partners | Growth |
| Loan officer website | Gives each loan officer a place to capture leads | Growth |
| E-signature | Collects signatures on documents and disclosures | Core |
| Team messaging and tasks | Keeps conversations and to-dos tied to the file | Core |
Core tools
- Loan origination software
- Point-of-sale and borrower portal
- Document collection
- Credit reporting
- Product and pricing engine
- E-signature
- Team messaging and tasks
Growth tools
- CRM and marketing
- Loan officer website
1. Loan origination software
Loan origination software, also called a loan origination system (LOS), is the backbone. It holds your pipeline, every loan file, and the status of each one. For a brokerage, it should also give each person the right view: the owner sees the whole pipeline, a loan officer sees their files, a processor sees their queue, and a borrower sees only their own loan.
What to check: multi-role access, a clear pipeline view, and a standard way to send a finished file to lenders. For a step-by-step view of what this software manages, read our guide to the loan origination system workflow.
2. Point-of-sale and borrower portal
A mortgage point-of-sale (POS) system is the borrower-facing side of origination. The borrower fills in the application, uploads documents and checks where the loan stands, usually from a phone.
What to check: the application works well on mobile, borrowers can save and come back, and every answer lands in the loan file as data your team can use. More on this in our page on mortgage point-of-sale software.
3. Document collection
Every loan needs pay stubs, W-2s, bank statements, IDs and more, plus documents from third parties like title and insurance contacts. A document collection tool replaces the email inbox as the place those files arrive.
What to check: a checklist tailored to each borrower, secure upload for third parties who do not have an account, and some way to pull data from documents so your processor is not reading every page by hand.
4. Credit reporting
Brokers pull tri-merge credit reports through a credit reporting agency. The report decides which programs a borrower qualifies for and how the loan prices.
What to check: the borrower's authorization is captured and stored with the file, and the report attaches to the loan file without a download-and-upload step.
5. Product and pricing engine
A product and pricing engine (PPE) compares loan programs, eligibility rules and rates across the wholesale lenders you work with. For a broker, this is how you show a borrower that you shopped the market for them.
What to check: coverage of the lenders you use, how often pricing refreshes, and whether a chosen scenario can flow into the loan file.
6. CRM and marketing
A mortgage CRM tracks past clients, prospects and referral partners, and runs follow-up over months or years. Rate drops, anniversaries and refinance opportunities all live here.
What to check: whether leads from your website reach the CRM on their own, whether it knows when a lead becomes an active loan, and whether your team will use it every day. An unused CRM costs more than no CRM.
7. Loan officer website
Each loan officer needs a place to send referral partners and past clients: a page with their photo, contact details and a way to apply or ask for a quote. For many brokers, this is the first point of contact with a borrower.
What to check: the apply button starts a real application instead of sending an email, and quote requests land somewhere your team will see them. See our page on loan officer websites.
8. E-signature
E-signature collects signatures on applications, authorizations and disclosures. Many wholesale lenders send their own disclosures for signature, so you may need e-signature mainly for broker-side documents.
What to check: which documents your lenders sign on their own platforms, so you do not pay for signatures you never use.
9. Team messaging and tasks
Text threads and personal email scatter the history of a loan. Messaging and task tools built into the file keep every conversation with the borrower, processor and loan officer in one place, and make it clear who owes the next step.
What to check: messages and tasks live on the loan file, not in a separate app, and borrowers can reply without installing anything new.
How to choose mortgage broker software
Before you sign with any vendor, ask these six questions:
- Does data entered once reach every other tool? If a borrower's income gets typed in three places, you will find three different numbers.
- Can a borrower finish the application on a phone? Many will try.
- Can third parties upload documents without an account? Title and insurance contacts will not create logins for one file.
- How does a file get to the lender? A standard export such as MISMO 3.4 lets lenders import the data. Manual re-entry invites errors.
- How is it billed? Compare per-seat pricing with usage-based pricing against how your team grows. Our pricing page explains how CliQloan bills.
- How is borrower data protected? Ask about encryption at rest, access controls and audit trails, and ask for the answers in writing.
One platform or separate tools?
Separate best-of-breed tools give you the strongest option in each category, but you pay for it in integrations and in data your team copies between systems. One platform gives you a single file and one login, but no platform covers every category equally well.
Most brokerages land in the middle: one core platform for the pipeline, application, documents, credit and team communication, plus specialist tools for pricing and marketing. Choose the core first, then add specialists that connect to it.
Where CliQloan fits
CliQloan is a loan origination system (LOS) for mortgage brokers and loan officers. It covers the core of the list in one loan file:
| Tool category | What CliQloan provides |
|---|---|
| Loan origination software | Multi-role loan origination system for brokers, loan officers, processors and borrowers, with a shared pipeline and loan file |
| Point-of-sale and borrower portal | Guided, URLA-style digital application |
| Document collection | Guided document checklist, document intelligence on supported document types, and secure upload links for third parties |
| Credit reporting | Tri-merge credit with borrower consent |
| Loan officer website | Branded loan officer microsite with quote and pre-approval forms, plus pre-approval letters as PDFs |
| Team messaging and tasks | In-app messaging, tasks and status updates on the loan file |
| Third-party interfaces | Interfaces with appraisal, escrow and insurance providers, and with verifications such as employment verification |
| Lender handoff | MISMO 3.4 export |
CliQloan does not include a product and pricing engine, and it captures leads rather than acting as a full CRM, so keep your specialist tools for those jobs. CliQloan works with any lender's systems, which stay the system of record for underwriting and closing.
See the full picture on our page for mortgage broker software.
Frequently asked questions
What tools does a mortgage broker need to get started?
A new brokerage needs loan origination software, a way to take a digital application, document collection, credit reporting, access to lender pricing, and e-signature. A CRM and loan officer websites usually come next, once you have a steady flow of leads.
What is the difference between an LOS and a POS?
A loan origination system manages the loan file and pipeline for your team. A point-of-sale system is the borrower-facing part, where the borrower applies, uploads documents and checks status. Some platforms combine both in one product.
Do mortgage brokers need a CRM?
A CRM helps when you have more past clients and referral partners than you can track by memory, because it runs long-term follow-up for rate changes and refinances. A small or new brokerage can start with lead capture in its origination software and add a CRM as the database grows.
How do mortgage brokers submit loans to lenders?
Brokers submit files through each wholesale lender's portal, either by uploading documents and data or by importing a standard data file. MISMO 3.4 is the industry data standard for the application, so an export in that format lets a lender import the data without rekeying it.
Can one platform replace every mortgage broker tool?
One platform can cover the core jobs: pipeline, application, documents, credit and team communication. Most brokers still use specialist tools for loan pricing across lenders and for long-term marketing, and connect them to the core platform.