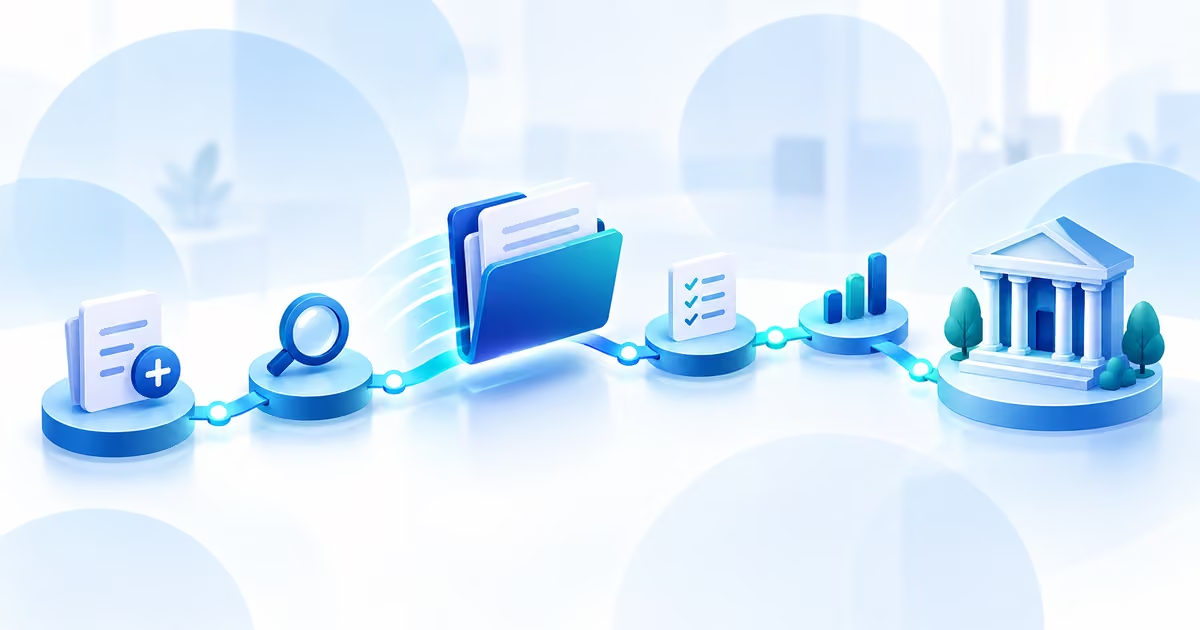
A loan origination system workflow is the order a mortgage file moves through from first contact to a funded loan: lead capture, application, disclosures, credit, documents, processing, underwriting, and closing. Each stage has an owner, a set of documents, and a handoff to the next person. Most delays happen at those handoffs.
If you run a brokerage, you know these stages already. This guide lays them out in order, shows who owns each one on a brokered loan, and points to the spots where files stall, so you can fix the slow parts first.
Key takeaways
- A mortgage file moves through eight stages, from the first lead to funding and post-closing.
- Under TRID, an application exists once you collect six specific pieces of information. That starts the three-business-day clock for the Loan Estimate.
- On a brokered loan, the broker runs the front half of the workflow. The lender owns underwriting, closing and funding.
- The stages a broker controls, from application to file submission, are where better software saves the most time.
What is a loan origination system workflow?
A loan origination system (LOS) is the software that holds a mortgage file together: borrower data, documents, credit, tasks and status. The workflow is the sequence that file follows, who acts at each step, and what has to be true before the next step starts.
Brokers and lenders see the same workflow from different sides. A lender's system is the system of record for underwriting and closing. A broker's origination software runs the front stages, from lead to a complete file, and then hands that file to the lender. When the handoff is clean, the lender can start underwriting without calling you back for missing pieces.
The 8 stages of the loan origination workflow
| Stage | What happens | Usually owned by |
|---|---|---|
| 1. Lead capture and pre-qualification | First contact, quick numbers, a quote or pre-approval letter | Loan officer |
| 2. Application | The borrower completes the Uniform Residential Loan Application | Borrower and loan officer |
| 3. Initial disclosures | The Loan Estimate and other early disclosures go out | Lender, or the broker on the lender's behalf |
| 4. Credit | A credit report is pulled with the borrower's authorization | Loan officer or processor |
| 5. Documents and verification | Income, asset and employment documents are collected and checked | Processor |
| 6. Processing and submission | The file is reviewed, packaged and sent to the lender | Processor |
| 7. Underwriting and conditions | The lender reviews the file and issues conditions | Lender |
| 8. Closing and funding | Final disclosures, signing, funding and post-closing | Lender, title and settlement agent |
Broker side
- 1Lead capture and pre-qualification
- 2Application
- 3Initial disclosures
- 4Credit
- 5Documents and verification
- 6Processing and submission
Lender side
- 7Underwriting and conditions
- 8Closing and funding
1. Lead capture and pre-qualification
A borrower reaches you through your website, a referral partner or a phone call. At this point you want rough numbers: income, assets, the price range they have in mind and a sense of their credit. With that, you can give a quote or a pre-qualification.
A pre-approval comes later and carries more weight, because it rests on a credit report and at least some verified documents. Sellers and agents take a pre-approval letter more seriously than a pre-qualification.
The common mistake at this stage is capturing the lead in one tool and starting the file in another. If your loan officer retypes the borrower's details into the application, you pay for the same data twice and risk a typo on day one.
2. Loan application (the URLA, Form 1003)
The application is the Uniform Residential Loan Application, known as Fannie Mae Form 1003 and Freddie Mac Form 65. The redesigned URLA became mandatory in March 2021. It covers the borrower's identity, employment and income, assets and liabilities, the property, the loan and a set of declarations.
The application also has a legal meaning. Under Regulation Z, an application exists once you have six pieces of information: the borrower's name, income, Social Security number to pull credit, the property address, an estimate of the property's value, and the loan amount sought. When you have all six, the Loan Estimate clock starts.
A digital application helps here. Borrowers can fill in sections in order, save their progress and come back, and the answers land in the loan file as structured data instead of a PDF someone has to read and retype.
Official reference: Fannie Mae's Uniform Residential Loan Application page.
3. Initial disclosures and the Loan Estimate
Once an application exists, the creditor must deliver or mail the Loan Estimate no later than the third business day after receiving it, under Regulation Z section 1026.19. On a brokered loan, either the broker or the lender may provide the Loan Estimate, but the lender stays responsible for getting it right and on time.
That split is where brokered files run into trouble. Agree with each lender on who sends disclosures, and make sure the application date in your file matches what the lender sees. The creditor also cannot charge fees beyond a bona fide credit report fee until the borrower has received the Loan Estimate and said they want to proceed.
For the full rule set, see our glossary entry on TRID.
4. Credit report
For most mortgage applications you pull a tri-merge credit report, which combines data from the three national credit bureaus. You need the borrower's authorization first, and you should keep a record of it in the file.
The report shapes almost everything that follows: which programs the borrower qualifies for, how the loan prices, and which debts the underwriter will count. Pull it early enough that surprises, like an old collection or a disputed account, show up before you have promised terms.
5. Documents and verification
This is the stage that eats the most time in a typical brokerage. For a salaried borrower you usually need recent pay stubs, W-2s, bank statements and photo ID. Self-employed borrowers add tax returns and business documents. Lenders then verify what the documents say through verification of employment, verification of income and verification of deposit.
Files stall here for predictable reasons. The borrower emails a screenshot instead of a full statement. A bank statement is missing a page. A pay stub goes stale while you wait for the rest. A guided checklist that tells each borrower exactly what to upload, and shows your processor what is still missing, removes most of the back and forth.
6. Processing and submission to the lender
Your processor reviews the file for completeness and consistency. Does the income on the application match the pay stubs? Do the bank statements explain every large deposit? Are third-party items, like a title contact or homeowners insurance details, in the file?
Then the file goes to the lender, either by upload to the lender's portal or as a data file. The industry data standard behind the URLA is MISMO version 3.4. When your software exports the application in MISMO 3.4 format, the lender can import it instead of rekeying it, which removes a common source of errors. You can read about the standard at MISMO.
7. Underwriting and conditions
The lender's underwriter reviews the file. Most conventional loans run through an automated underwriting system first: Desktop Underwriter from Fannie Mae or Loan Product Advisor from Freddie Mac. The underwriter then approves the loan with conditions, suspends it pending more information, or denies it.
Conditions come back to you. The lender may ask for an updated bank statement, a letter explaining a credit inquiry, or a signed document from a third party. Meanwhile, the appraisal, title work and insurance move forward. The faster you can collect condition documents from borrowers and third parties, the sooner the file reaches clear to close.
If the lender declines the application, the Equal Credit Opportunity Act and Regulation B set rules for notifying the borrower. See our glossary entry on ECOA.
8. Closing, funding and post-closing
After clear to close, the borrower must receive the Closing Disclosure at least three business days before consummation. The settlement agent coordinates signing, the lender funds the loan, and the file moves into post-closing: final document review, delivery to the investor and servicing setup. Settlement practices fall under RESPA.
For a broker, this stage is mostly about communication. Borrowers want to know the closing date, what to bring and when they get their keys. Keep them updated from the same file you have used since stage one.
Where the loan origination workflow slows down
The underwriting stage gets the blame, but in many brokerages the lost days sit earlier in the file. Watch for these five patterns:
- Retyping data. The same borrower details go into a lead form, an application, a credit request and a lender portal. Each copy is a chance for an error.
- Documents by email. Attachments land in personal inboxes, get renamed badly, and nobody knows which version is current.
- Status calls. Borrowers and agents call to ask where the loan stands because they cannot see it themselves.
- Third parties without access. A title contact or insurance agent has a document you need, but no easy way to send it securely.
- Unclear handoffs. A file waits two days because the loan officer thinks the processor has it, and the processor thinks the loan officer does.
How to map your own workflow in one afternoon
You do not need a consultant to find your bottleneck. Try this with your team:
- Pull your last ten funded files.
- For each one, write down the date it entered each of the eight stages above.
- Find the longest gap between two stages. That gap is your first fix.
- List every place where someone typed data that already existed somewhere else.
- Name one owner for every handoff, and write it down where the whole team can see it.
Fix one stage, measure the next ten files, then move to the next gap.
Where CliQloan fits in the workflow
CliQloan is a loan origination system (LOS) for mortgage brokers and loan officers. It runs stages 1, 2, 4, 5 and 6 of the workflow in one shared loan file, and connects the third parties your file depends on:
- Lead capture: each loan officer gets a branded microsite with quote and pre-approval forms that feed a leads list, and pre-approval letters are generated as PDFs.
- Application: borrowers complete a guided, URLA-style digital application step by step.
- Credit: tri-merge credit with borrower consent.
- Documents: a guided checklist tells each borrower what to upload, document intelligence extracts data from supported document types, and third parties such as a title or insurance contact can upload through a secure link without creating an account.
- Third parties: CliQloan provides interfaces with appraisal, escrow and insurance providers, and with verifications such as employment verification.
- Collaboration: brokers, loan officers, processors and borrowers work from the same file with in-app messaging, tasks and status updates.
- Submission: the finished file goes to your lender as a MISMO 3.4 export.
CliQloan works with any lender's systems, which stay the system of record for underwriting and closing. CliQloan does not make underwriting decisions, and it does not generate or deliver TRID disclosures.
See how it works for mortgage brokers, how the mortgage point-of-sale experience looks from the borrower's side, and how document intelligence and credit fit into the file. For a wider view of the software a brokerage runs on, read our guide to mortgage broker tools.
Frequently asked questions
What are the stages of loan origination?
Loan origination has eight stages: lead capture and pre-qualification, application, initial disclosures, credit, documents and verification, processing and submission, underwriting and conditions, and closing and funding. On a brokered loan, the broker handles most of the first six and the lender handles the last two.
What starts the Loan Estimate clock?
The clock starts when you have six pieces of information: the borrower's name, income, Social Security number, the property address, an estimate of the property's value, and the loan amount sought. The creditor must then deliver or mail the Loan Estimate no later than the third business day after receiving the application.
Who is responsible for the Loan Estimate on a brokered loan?
Either the broker or the lender may provide the Loan Estimate to the borrower. The lender remains responsible for making sure its content, timing and delivery meet the rule.
How is a broker's workflow different from a lender's workflow?
A broker's workflow centers on the front of the file: finding the borrower, taking the application, pulling credit, collecting documents and submitting a complete file. A lender's workflow centers on underwriting, disclosures, closing and funding, and the lender's system is the system of record for those stages.
What is MISMO 3.4 and why does it matter?
MISMO 3.4 is the mortgage industry's data standard behind the redesigned Uniform Residential Loan Application. When a file is exported in MISMO 3.4 format, a lender can import the application data directly instead of rekeying it, which saves time and cuts errors.